


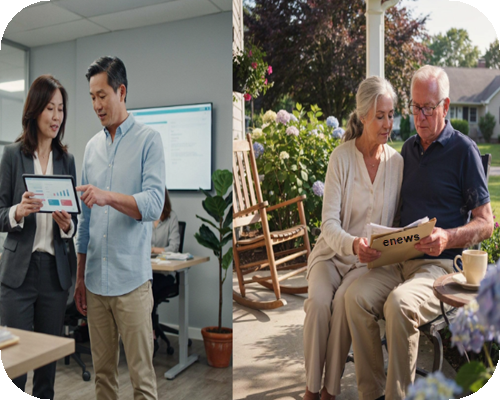
Health insurance planning changes as income, family responsibilities and healthcare needs evolve. During working years, people usually have regular earnings and may also receive employer-provided medical cover. Retirement changes this structure because income may become more limited and personal health protection often becomes more important.
Planning therefore needs greater attention to affordability, policy continuity, medical needs, family responsibilities and protecting retirement savings from financial pressure.
Regular Income Changes to Retirement Income
During working years, health insurance premiums are usually paid from monthly income, giving people flexibility to review cover as responsibilities grow. After retirement, premiums may come from pension income, investments or savings, so long-term affordability becomes more important.
Premiums should fit comfortably within the retirement budget while accounting for household expenses and healthcare needs. Policy decisions should also consider future financial stability and whether premiums can continue to be paid comfortably once regular salary income stops.
Responsibility for Parents May Shift Towards Personal Health Needs
During working years, adults may manage household insurance along with health insurance plans for parents. As retirement approaches, personal healthcare planning usually needs greater attention. Parents’ healthcare needs may need to remain separate from retirement planning so that each person’s requirements can be assessed individually.
Medical history should also be considered when reviewing future cover, while policy structures should be checked to ensure they remain appropriate for different family members and their changing healthcare needs.
Employer Cover May No Longer Be Available
Many salaried individuals receive health insurance through their employer. This cover may support medical needs during employment but can change or stop after retirement. Personal insurance therefore becomes more important, particularly for people who have depended mainly on workplace benefits.
Before retirement, it is useful to check how much personal cover exists outside employer insurance, whether it suits future medical needs and whether continuity can be maintained after employment ends.
Healthcare Requirements Need Closer Attention
In younger working years, insurance planning may focus mainly on possible future medical expenses. With age, existing conditions, regular consultations and hospitalisation needs may require closer attention, making policy reviews more detailed near retirement.
The available sum insured should be reviewed along with access to network hospitals near the place of residence. It is also important to understand co-payment requirements, room eligibility, related policy conditions and any waiting periods that may apply to existing or specified medical conditions.
Family Coverage Requirements May Change
Health insurance during working years often includes a spouse, children or other dependants. By retirement, children may become financially independent, so the same family structure may no longer remain suitable.
Someone managing medical insurance for a family of 4 may therefore need to review who still requires shared cover. The existing family policy should be assessed for practicality, while separate cover may be considered when medical needs differ or when dependants become financially independent.
Policy Continuity Becomes More Important
Health insurance continuity matters at every stage, but it becomes particularly relevant close to retirement. Keeping a policy active can help preserve eligible continuity benefits built over time, subject to policy terms and applicable regulations. Planning should therefore focus on avoiding unnecessary gaps between policies and reviewing renewal dates before expiry.
Before changing cover, it is also useful to understand portability or migration provisions, check how waiting periods are treated and read policy terms carefully before replacing an existing policy.
Protecting Retirement Savings Becomes a Greater Priority
During working years, regular income may help absorb some medical expenses. After retirement, larger healthcare costs may need to be paid from savings intended for everyday living and future needs.
Insurance planning therefore becomes more closely connected with preserving retirement funds. Coverage should match both healthcare requirements and financial capacity, while deductibles and co-payments should be understood clearly.
Policy Reviews Become More Health Focused
Insurance reviews during working years may follow marriage, childbirth, a job change or an increase in income. After retirement, reviews are more likely to focus on medical needs, hospital access, affordability and continuity.
A regular review should check whether current coverage still matches healthcare requirements and whether suitable network hospitals remain accessible. Claim procedures, documentation requirements, renewal terms and benefit conditions should also be understood.
Final Thoughts
Health insurance planning changes after retirement because income, family responsibilities and healthcare priorities are no longer the same. During working years, the focus is usually on building cover and supporting dependants. Retirement places greater emphasis on affordability, continuity, medical needs and protecting savings.
Reviewing insurance before retirement can make the transition more organised, although the suitable approach depends on individual finances, medical history, family structure and policy terms.
Howie Hubert
Recent Articles
Prescott Fine Art Launches Monthly Art Auctions at Pine Ridge Marketplace
Town of Chino Valley Selected for Community Beautification Project as APS Celebrates 140 Years in Arizona
City of Prescott Reminds Citizens of Political Sign Regulations and No Campaign Materials in City Facilities
Trust for Public Land, Local Partners Secure Permanent Protection of Upper Sullivan Canyon, Safeguarding Key Verde River Rock Climbing Site