


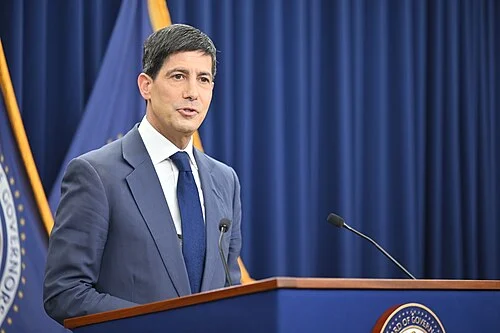
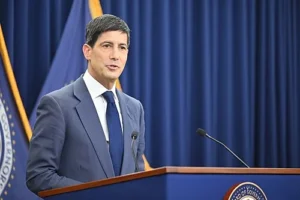
Photo: Chairman of the Federal Reserve, Kevin Warsh
For the first time since July 2023, the Federal Open Market Committee appears poised to raise the target range for the federal funds rate when the committee’s two-day meeting concludes this week.
Just 10 days ago, the probability – at least according to CME Group’s FedWatch tool – that the FOMC might raise the key rate was about a 60-40% coin toss.
But then on Friday, while the United States was commemorating 25 years since the 9/11 attacks, the latest Consumer Price Index report provided a most unwelcome Friday news dump, pivoting things toward a much more predictable outcome this week.
Overall inflation, according to the CPI, is still what the Fed would likely term “meaningfully” above its long-term goal of 2%. The annual pace of 3.4%, as of August, tacked on 0.4% over July’s numbers. Core prices, stripping out volatile sectors such as energy and food, rose 2.4% year-over-year.



All that amounts to the FedWatch tool now predicting about an 86-87% likeliness that the key rate will be raised a quarter point, to the target range of 3.75% to 4%.
Couple that with daily mortgage rates topping 7% for the first time in more than a year as of last Thursday, and economic elements seem trending in the wrong direction for prospective home buyers and borrowers.
However, Eric Bernstein, president and co-founder of LendFriend Mortgage, reminds us that as interconnected Federal Reserve policy is to the housing market, the relationship isn’t in automatic lockstep.
“The biggest misconception is that if the Fed raises rates by 0.25%, mortgage rates automatically rise by 0.25%,” Bernstein tells The Mortgage Note. “Fed rate hikes don’t work that way. Mortgage rates move based on expectations. A lot of the September hike is already priced into the bond market, which is why mortgage rates jumped this week as a hike became all but guaranteed.”
Of course, it was only seven weeks ago – after the Fed’s last meeting – that Chairman Kevin Warsh expressed hope that his agency could become less of a bellwether than it has been going forward.




“Market participants are learning to play the ball, not the referee – and market prices will continue to respond in the direction and magnitude they see fit,” Warsh said July 29. “This is, in my view, a change for the better.”
Susan Hume, PhD, associate professor of finance in the School of Business at The College of New Jersey, calls it “a test of wills” this week, as Warsh weighs his pledge to be data-driven alongside the whims of President Donald Trump, who has consistently and staunchly argued for lower interest rates.
In fact, Trump took to Truth Social, drawing on a stronger-than-expected jobs report to pair his desire for downward motion from the Fed with a potential escalation of a trade war that has most recently engaged Canada.
“Lower the interest rates because the U.S.A. is a much stronger credit than it was just a short time ago!” Trump wrote on the social media platform, adding, “LOWER THE RATE OR I’LL STOP TRADING WITH COUNTRIES WITH WHICH WE HAVE A DEFICIT.”
Crucial to Trump’s thinking, Hume says, is that lower interest rates will reduce international investment flows and lower the dollar exchange rate with both trading and investing partners. He has urged Warsh to “get smart,” Hume explains.
“President Trump is jawboning his newly appointed Fed Chair to make short-term interest rates come down,” Hume tells The Mortgage Note. “He argues that high rates put the U.S. at an economic disadvantage compared to countries with lower rates.”
Hume also says there’s a chance that the Fed lowering interest rates may destabilize the U.S. dollar, even if those lower rates would, domestically, inevitably bring mortgage rates down.
That’s why Bernstein says what Warsh says publicly on Wednesday, after the FOMC’s decision has been made, could ultimately matter more than the decision itself. For his part, Warsh has said he will continue post-meeting press conferences at least through the end of 2026.
“If the Fed hikes 0.25% and Warsh makes it sound like this is a one-and-done move, mortgage rates could stay flat or even fall,” Bernstein says. “If he signals that another hike could come in October or December, mortgage rates could move higher immediately following the press conference.”
(Interestingly, without even knowing the outcome of this week’s meeting, FedWatch predicts at least a 40% chance of another quarter-point hike forthcoming in October.)
And here is where Warsh’s intent for markets to be less reliant on what the Fed says hits a snag.
Hume mentions the “Impossible Trinity” of the Mundell-Fleming policy model, in which a country can pick only two of three economic goals: free-flowing money across borders, a stable fixed currency value, and independent control over its own interest rates and money supply.
Seeing things through this lens, it may be the Fed’s very independence that makes it so influential. Changing that, Hume suggests, would be a protracted process.
“Moving to a less independent Federal Reserve where there is no longer control over interest rates and monetary policy would change this policy dynamically and require our exchange rate to be fixed, not free-floating,” Hume says. “This unlikely shift would require an overhaul of the global monetary system and Congressional approval.”
The bottom line, as it always is: In the short term, what does this mean for those hoping to make a move in the housing market?
“Higher mortgage rates hurt affordability, but they also reduce demand,” Bernstein says. “Fewer buyers in the market usually means more negotiating power for the buyers who remain. That can show up through lower purchase prices, seller credits, or money toward a rate buydown, which can offset some of the higher borrowing cost. So I would not automatically wait for lower rates. If rates fall, demand could come back quickly. You may get a better rate but pay more for the house and have less leverage.”

PATRICK LAVERY | The Mortgage Note
Recent Articles
Chino Valley Animal Shelter Reduces Adoption Fees as Shelter Reaches Capacity
Findlay Subaru Prescott Hosts “Puppy Wish Party” to Surprise Local Wish Kid with Her Dream Dachshund
Victory Wealth Services Announces Annual Sock Drive to Support Local Homeless Shelters
Free Garden Classes for September at Watters Garden Center